Are we witnessing an intelligence explosion?
From Luis Garicano and Alex Imas:
Hence AI capabilities improved 1.91 times faster after October 2025, but R&D spending grew 6.19 times and the technical workforce 3.10 times. So measured capability gains per dollar fell by approximately 69%, and measured gains per technical employee-year decreased by 38%. These figures are accounting; nothing causal can be inferred…
The accounting exercise we just did cannot tell us which. It shows that returns per dollar decreased: spending multiplied by 6.2 and the pace of progress by 1.9. But two different causes for this are possible. One is congestion: the effort is getting less productive as it increases, because it is hard organizationally to increase the budget by more than five times in a year. The other possibility is that each advance is harder than the last. With enough congestion, these same two numbers are even consistent with each advance making the next one easier, which is what an explosion requires. To know whether a break is needed, we must know what an unchanged relationship would have delivered…
In sum our finding is consistent with that of Bloom and his coauthors: ideas are getting harder to find in AI too, and maintaining the rate of improvement requires ever larger increases in inputs.
Overall the idea of an intelligence explosion still remains to be demonstrated.
Friday assorted links
The Economics of Rent Controls
I appear on Ryan Bourne’s excellent new podcast, The Economics of It. We discuss The Economics of Rent Controls drawing on my essay, Rent Control: The Ceiling Trap. It’s a very good discussion. Here’s one bit (edited slightly to remove some ums for reading and to fix a date I got wrong from memory):
RB: And in your essay you talk about some like truly insane ways that people are trying to signal to landlords that they’ll be good tenants in Oslo. I know you talk about that example.
Tabarrok: Yeah, so in Oslo they had rent controls for many years, but then they got rid of them in 1982 (fixed, AT), And there’s a great paper by Are Oust who looks at what happened. When the rent controls were in place, amazingly he found just like Friedman and Stigler found in San Francisco in 1906 that in Oslo the renters advertised I need an apartment, okay? Won’t you rent me an apartment? And as part of their advertisement they would say I’m willing to look after your cat, I’m willing to, you know, shovel the snow.
And on the other side the landlords would say, well, I’m looking for a good Christian. Uh you know, I’m looking for a uh a heterosexual, you know, single-family couple, whatever—these kinds of things. Sometimes literally advertised, sometimes this would happen, under the table. Um there would be things like you would have to pay uh months–sometimes years–you have to pay your rent years in advance. You know, all kinds of ways in which because of the shortage of apartments, it was the renters who had to advertise…
Even companies would say I’ve got a great employee. Please won’t you get them an apartment for me? Okay. 1982 the rent controls were lifted and suddenly the advertisements switch 100%. So suddenly it’s no longer the renters who are advertising. It’s now the landlords I’ve got a great apartment. And uh all of this stuff, are you willing to shovel the driveway, take care of my cat? It all goes away.
Outlook email is still down
And GMU is on the Outlook system. If you need to reach me, you can extrapolate my gmu address to my gmail address, or try Twitter, or use your imagination in other ways. Sorry for the inconvenience!
(Although it seems my Outlook system just opened up, albeit with an incomplete email delivery so far!?)
The U.S. Federal AI Observatory
Federal AI at a glance
41 agencies · 3,611 reported use cases · OMB 2025 Inventory. Portfolio size reflects reporting, not performance.
From Irakli Petriashvili of Tblisi, here is the site.
Do not overrate zero-sum status-seeking
If people really preferred relatively higher income in a poorer society, then those born in Western Europe and the US would be saving up their money so they could live like kings in Africa. Very few people of middle- or upper-class status in poor countries would try to get to the West. Obviously, what we observe is precisely the opposite. Doctors from Africa will come to America in order to drive a cab if their license to practice medicine isn’t recognized. Research on Middle Eastern and African migrants to Europe shows that they aren’t the poorest of the poor, but are relatively well off for where they come from. There are a lot of stories about how terribly South Asian migrant workers are treated in the Arab Gulf, but this causes no problem in recruiting laborers who want to earn a higher income.
Here is more from Richard Hanania.
My Barcelona talk on AI
Thursday assorted links
1. New Texas A&M podcast: Economists Unscripted.
2. A new tool for AI-proof homework assignments. “It’s called deb8.tv — students get paired and have live video debates with one another.”
4. Sulfuric acid as a basic medium for life? (NYT)
5. The fascination of underwater archaeology (Atlantic).
6. NYT obituary for Richard Posner. And Cass Sunstein on Richard Posner.
The Everywhere Rent Seekers
Zidar and Zwick have a good post on the political power of billionaires versus the power of many millionaires, based on their excellent book The Everywhere Millionaire.
First, they point out that despite the attention given to (some days) trillionaires and billionaires, the combined wealth of the Everywhere Millionaires, the dentists, the car dealers, the mid-size business owners, is far larger.
…it’s important to put the scale of Forbes billionaire growth into perspective with the other rich and powerful actors in American society. Even at the very frothy public market valuations of the current moment, the Forbes list amounts to around $8 trillion or roughly 4.3% of total household wealth. Meanwhile, based on the most recent SCF, Everywhere Millionaires are probably worth more than $63 trillion or 38% of total household wealth.
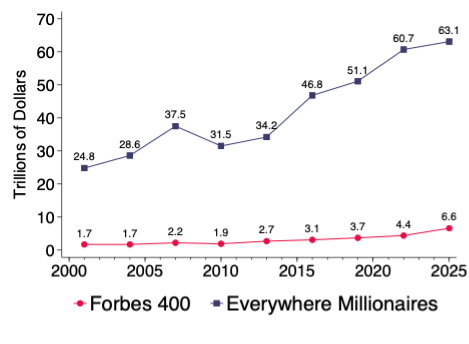 Second, the power of the billionaires is often exaggerated relative to the power of the millionaires who have money and votes:
…Elon didn’t want the massive tax cuts in the OBBBA extended, which did not go to the tech billionaires. He didn’t benefit from the reduced EV demand, which came when the EV credits were abolished. He benefitted little from the new deduction for car loan interest passed in that bill, since financing car purchases is a small part of Tesla’s business.
Who drove these changes and reaped the rewards? The Everywhere Millionaire car dealers who reside in nearly every Congressional district and represent many of them directly. Elon lost big in the midterm election, despite spending half a billion dollars. Meanwhile, dozens of Everywhere Millionaires will return after the election to the new Congress and to state and local government positions across the country.
That’s all correct, but there is an even more telling and absurd asymmetry. In many states it is illegal for Tesla to sell its cars directly to consumers! Namely, Alabama, Arkansas, Connecticut, Iowa, Kansas, Louisiana, Montana, Nebraska, New Mexico, North Dakota, Oklahoma, South Carolina, South Dakota, Texas, West Virginia and Wisconsin.
Amazingly, that list includes TEXAS! Tesla builds the Model Y in Austin but they cannot sell directly to Texans who instead must technically buy their car from Tesla in another state. That shows you the power of the everywhere rent seekers.
USG assets are worth less than Arnold Kling had thought
Federal oil and gas rights are worth about $625 billion on the paper’s own method, down 75% in real terms since 1981. Federal land has gone the other way, to roughly $1.1 trillion to $1.6 trillion. Land, not minerals, is now the larger asset.
Here is the full post.
My excellent Conversation with Terence Tao
Here is the audio, video, and transcript. Here is part of the episode summary:
Tyler opens by asking Terence what it feels like to contemplate Euler’s identity, quantum mechanics, the Riemann hypothesis, and Gödel’s incompleteness theorem, before moving into why mathematical history gets stripped out of classrooms, whether abstract math is a lottery ticket or a unified whole, string theory’s beauty versus its lack of confirmation, why real analysis arrived so late, why zero took until the 7th century to be invented, game theory, the Black-Scholes model, Bostrom’s simulation argument, and Newcomb’s paradox, math education and the case for teaching more statistics, Tao’s view that AI has pushed mathematics from an era of “proof scarcity” into “proof abundance,” what that means for the research paper, why video talks may become more valuable than papers themselves, Tao’s favorite Hong Kong action movies, his unconventional path through an Australian university at age 13, his most unusual work habit, his verdict on the Collatz conjecture, and more.
Excerpt:
COWEN: When you look at mathematical economics over the last two decades, is it interesting to you as math, or is it just a bunch of people doing something different that, to you, is low level?
TAO: Oh, yes, I was always fascinated by economics. I love game theory, and actually often there are pure math problems where it’s actually good to think in game theory terms. In analysis, you have all these complicated statements, like for every ε, there exists a δ, blah, blah, blah. It looks very intimidating, but if you phrase it as a game, your opponent is giving you an ε, you need to counter that ε with a δ of your own. If you view it as a game, then actually you can talk about strategies and who’s ahead, who’s behind. It actually activates really good modes of thinking.
I’ve used economic thinking in my own work. We talk about cost functions and minimizing loss. There are lots of concepts. Ricardo’s law of comparative advantage, I use that to run my life. There are so many things I can do. What do I choose to spend my time on? It’s actually a very useful principle: comparative advantage.
Economics, I find it’s a very good arena to understand the difference between models and reality. Physics, we’re spoiled because we’ve had these great physicists who’ve created these very accurate models of the real world, classical mechanics, quantum mechanics, and they’re very well tested and very accurate. You can just go to town exploring their consequences and still predict reality. Economics is a much more mixed situation where you have models, and sometimes they predict the real world very well, but sometimes they don’t.
In addition to doing the math, you also have to do the modeling, and you have to understand the limits of when a model starts breaking down and what you need to do to adjust it. I find that fascinating. It’s somewhere between the hard sciences and the social sciences. There’s enough hard models that you can do math, but there’s also enough real-world messiness that you have to also grapple with the subjectivity. As an outsider, I find it a really fascinating subject.
COWEN: When you looked at the Black-Scholes model, were you shocked when the probability doesn’t matter? Was that beautiful to you?
TAO: Yes, yes, yes. There is a special feature of Gaussian fluctuations that you can price options just by knowing risk. There is one algebraic miracle that makes this work. Normally, predicting future costs of anything is just an intractable problem, and there just happens to be this miracle. If you have Gaussian fluctuations, then it is beautiful. This is actually a really good example of when you need to know when the models work and when they don’t work. If you don’t have Gaussian fluctuations, then actually Black-Scholes is somewhat dangerous to use, especially if you compound it into derivatives over and over again. Again, that’s an old story. You know what happened in 2009.
Self-recommending, and of interest throughout. There is some on AI, but he has spoken so much on that topic lately I decided not to emphasize it. And Terry does have a new book out, namely Six Math Essentials.
Richard Posner, RIP…
Experimentally validated digital twins
There is a new paper by Raj Chetty, Jamie Fogel, Lawrence F. Katz, Kadeem Noray, Sonya Porter, and James Reisinger:
Modern program evaluation prioritizes evidence from randomized controlled trials (RCTs) because prior research found that observational estimates of program impacts often diverge substantially from experimental benchmarks. We revisit this finding — which was based on small survey datasets — in the era of large-scale administrative data. Using anonymized income tax records covering all American adults between 1999 and 2025, we estimate the effects of workforce training programs on earnings by using machine learning models to predict counterfactuals from rich data on prior work histories, demographics, and residential locations. Rather than testing whether our observational estimates are unbiased, we use 37 RCTs to estimate the distribution of their bias. We find that our machine learning estimates closely match the RCT estimates, with root mean squared error (RMSE) comparable to that of the RCTs themselves. Our method reduces RMSE by 60% relative to parametric estimators used in prior work because our larger samples and richer covariates permit more flexible, higher-dimensional models of the counterfactual. Applying our method to a broader set of sites and enrollment years beyond the experimental sample, we find that treatment effects on earnings vary substantially across locations and over time, even within a given program. Programs that place more participants into target-sector jobs generate the largest earnings gains, with impacts that persist even after participants leave their initial jobs. These findings provide guidance for improving job training programs and, more broadly, illustrate a scalable approach to program evaluation that uses observational data to construct experimentally validated “digital twins.”
Work of this sort is going to revolutionize economic method.
Wednesday assorted links
1. “We were discussing this today in office: future paper is 5 pages (what’s question, where is lit now very briefly, what do we do, what do we find), with all details left to a long appendix, hyperlinked, with rigorous AI review. We would read many more papers in that world! Agree?” Kevin Bryan.
2. “Norway now has more than 2,000 underwater AI laser robots shooting lice off its salmon”
3. Coefficient Giving is looking to support new types of organizations.
4. The future of fermented food in Africa.
5. Shruti and Henry Oliver podcast with transcript on Gulliver’s Travels.
What should I ask Simon Sebag Montefiore?
I will be doing a Conversation with him, most of all about his new and very good book The Cauldron: The Making of the Modern Middle East. He has many other excellent books too, including on Russian history and some fiction. Here is his home page, here is his Wikipedia page.
So what should I ask him?